
 Read NV on Google
NBU Press Service
According to KPMG’s
M&A Radar H1 2026, Ukraine’s M&A market has continued to maintain
stability in the first half of 2026.
Overall deal volume increased by 14% year-on-year, while total disclosed deal value for the transactions valued in excess of USD5 million was down just 5% compared with the same period of 2025.
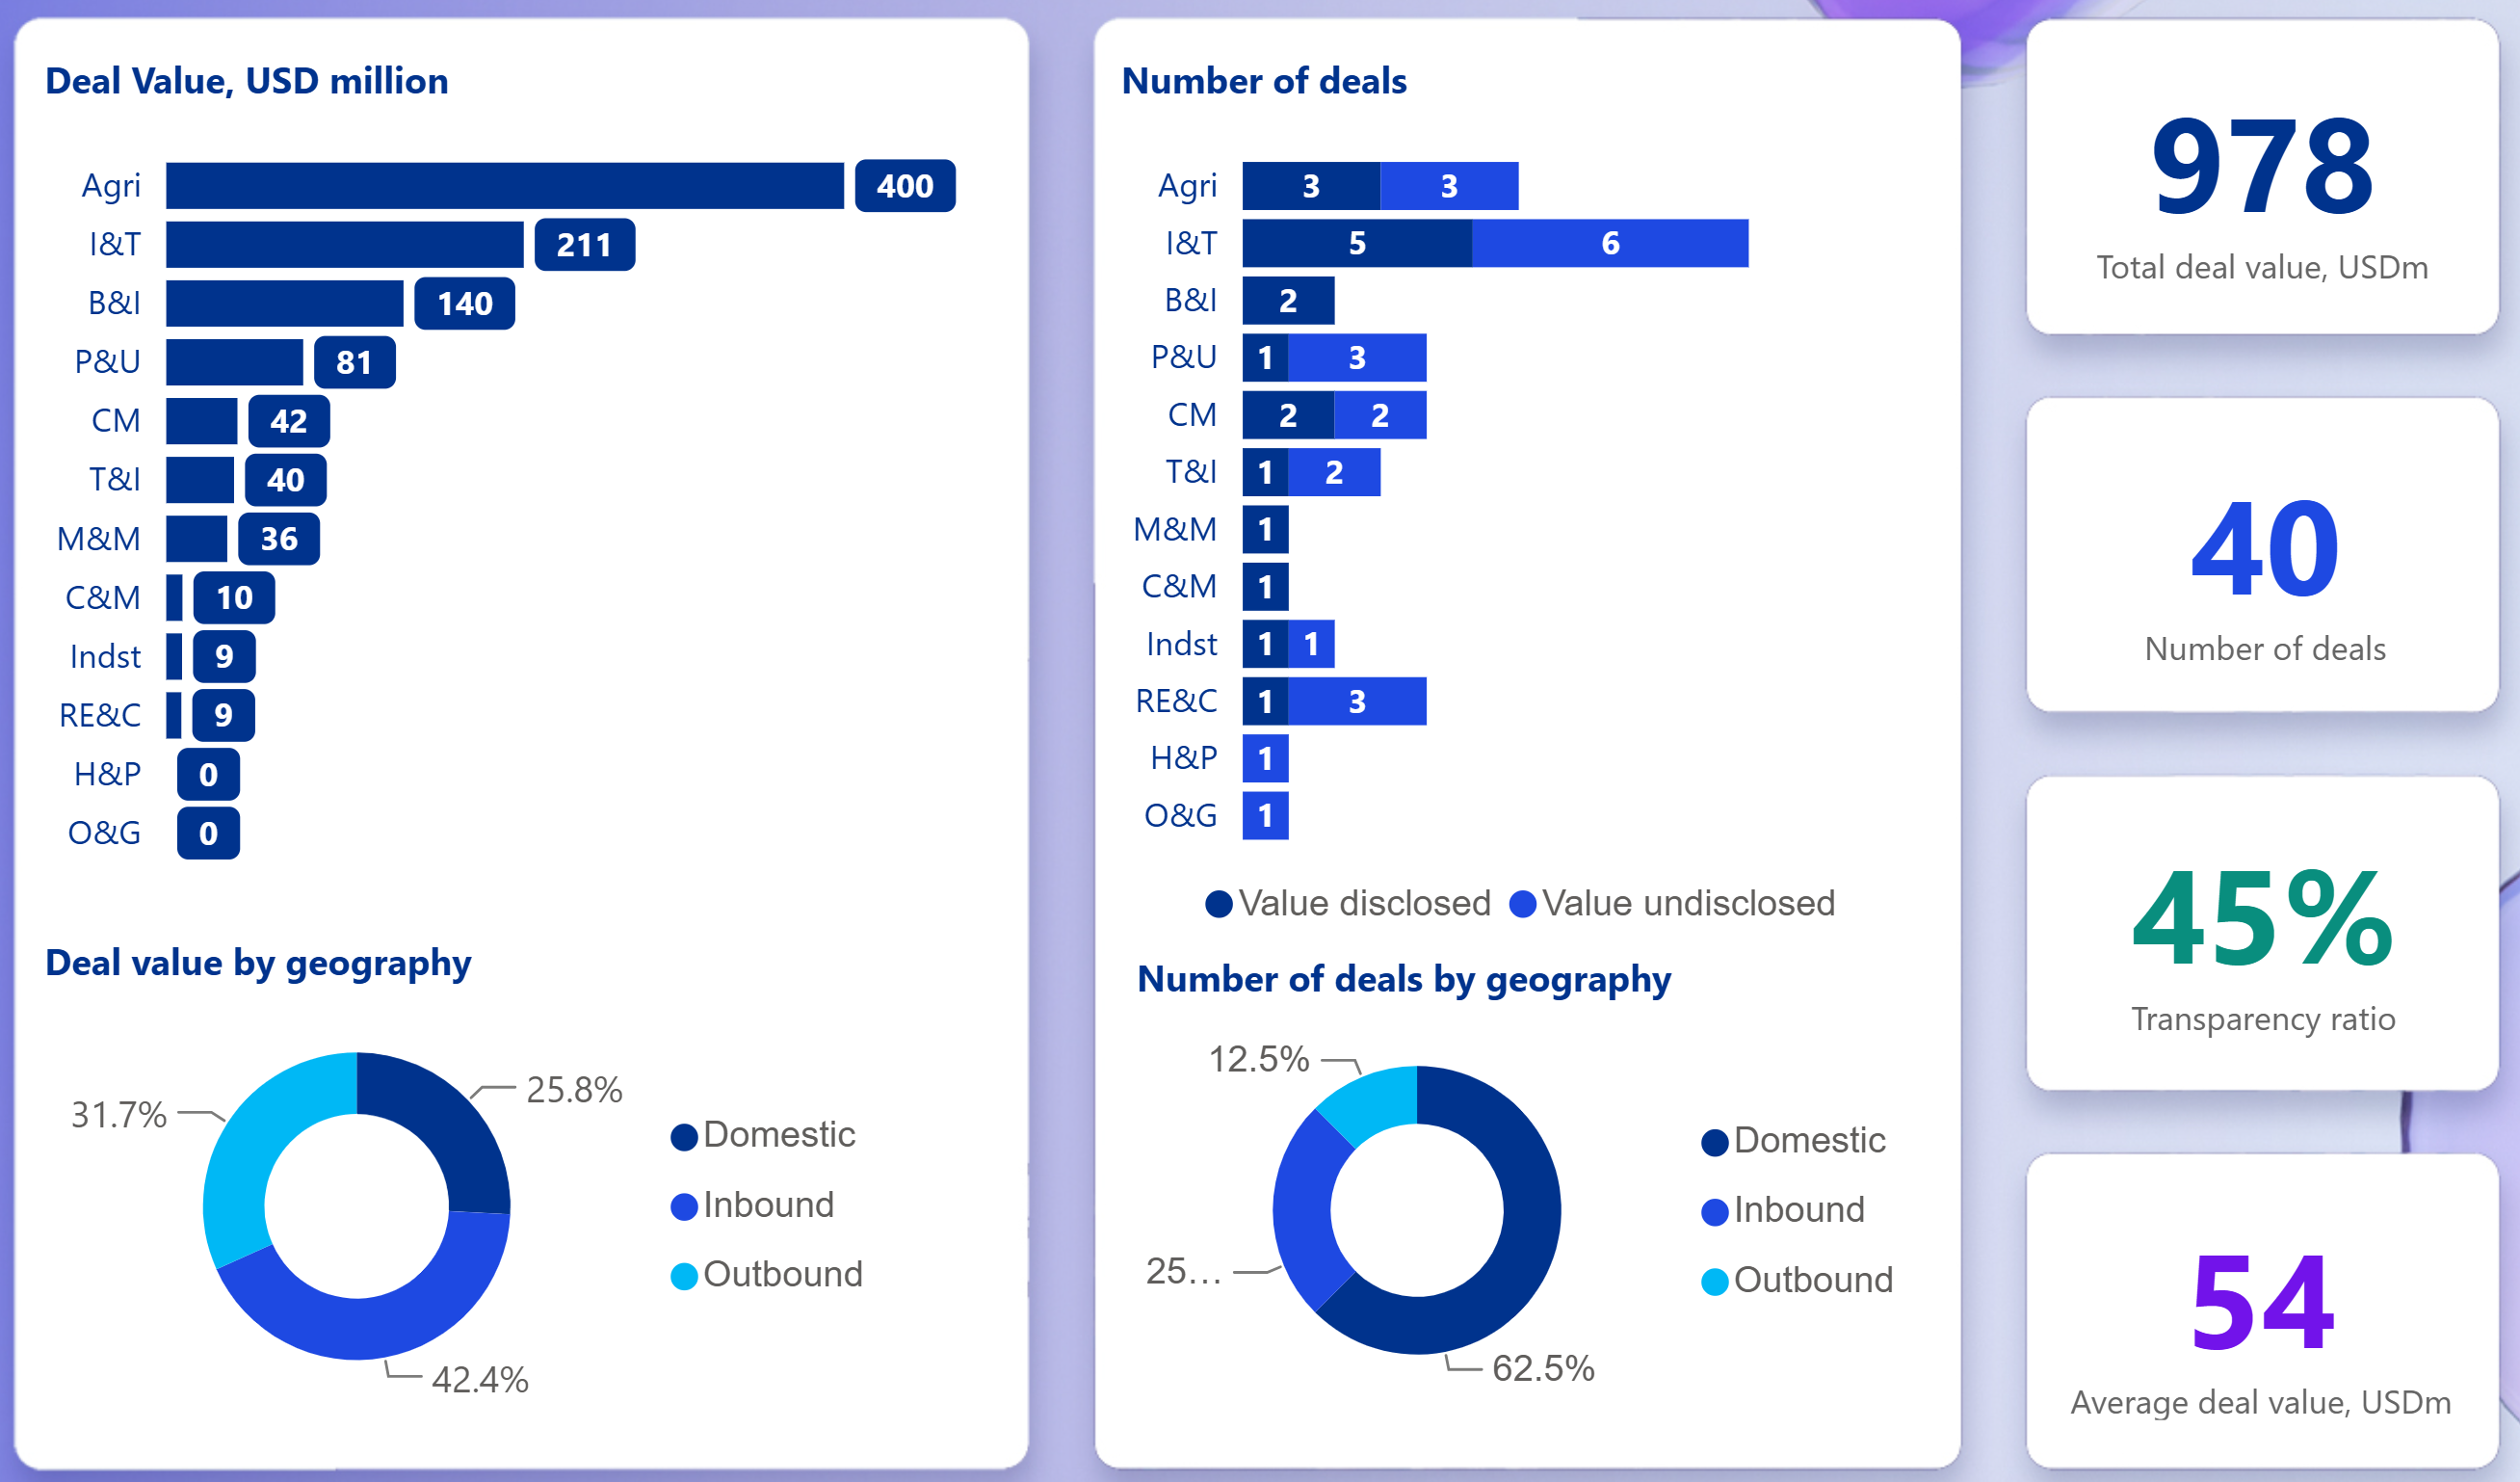
Furthermore, with only 45% of transactions disclosing value in H1 2026 (compared to 63% in H1 2025), a less transparent market environment at the beginning of the year indicates that reported market size may not fully reflect underlying activity, with total deal value potentially improving as the year progresses and a fuller picture becomes apparent.
According to Svitlana Shcherbatyuk, Partner, Head of Transaction Services KPMG in Ukraine, recent results also suggest that transactions continue to progress where asset quality is strong and investors are prepared to manage Ukraine-specific execution risks.
“Despite the prolonged impact of the war, investors continue to evaluate opportunities in Ukraine. While investment decisions remain highly selective, interest remains focused on assets with strong fundamentals where the strategic rationale for the investment decision is clear, in addition to a proven ability to operate under wartime conditions.”
By the numbers: trending steady
Ukraine recorded 40 M&A transactions in H1 2026,
compared with 35 in the same period of 2025. Total disclosed deal value reached
USD978 million, only slightly below the USD1.03 billion recorded a year earlier
and subject to a significantly lower level of transaction value disclosure by
comparison.
The largest deal of H1 2026 was agrifood group MHP’s USD290
million agreement to acquire a stake in Greek meat producer and distributor Th.
Nitsiakos AVEE, continuing MHP’s strategic pursuit of expanding into
international markets.
Three additional transactions exceeded USD100 million in value:
- Language learning platform Preply’s USD150 million Series D funding round, elevating the Ukrainian-founded education technology company to unicorn status.
- Kapenata Limited’s acquisition of agricultural holding Agro-Region Group for more than USD100 million.
- Polish insurance company PZU SA’s agreement to acquire Ukraine’s largest life insurer MetLife Ukraine in a deal estimated at approximately USD100 million.
Innovations and technology, agriculture, and energy sectors lead deal activity
Innovations and technology stayed Ukraine’s most active
sector by M&A deal volume, accounting for 11 transactions in H1 2026, while
agriculture continued to be one of the key drivers of the Ukrainian M&A
market; accounting for 41% of total disclosed deal value.
Power and utilities, meanwhile, recorded one of the
strongest increases in activity, with deal volume rising from one transaction
in H1 2025 to four transactions in H1 2026.
Domestic deals remain the foundation of M&A market activity
Following trends seen in 2025, domestic transactions
continued to account for the largest share of Ukrainian M&A activity by
volume, with 25 deals in H1 2026 recorded in market mainstays such as
agriculture and innovation and technology, alongside other sectors such as
power and utilities and real estate and construction which have both seen
increased activity following concerns about the impact of Russia’s full-scale
invasion on Ukrainian infrastructure.
This trend was exemplified by telecoms group Kyivstar’s
USD80.8 million purchase of six solar power plants in the Lviv region, while
service station chain OKKO Group also expanded its renewable energy portfolio
through investments in wind power projects. Such moves reflect a growing
corporate focus on energy security and resilience in the face of potential
operational challenges.
While disclosed domestic deal value declined from USD675
million in H1 2025 to USD253 million in H1 2026, it is also worth noting that
domestic transactions in Ukraine traditionally feature lower levels of value
disclosure and often become more transparent later in the year.
Inbound M&A activity increases
Despite the ongoing predominance of domestic M&A by
volume, H1 2026 saw an increase in inbound M&A activity compared to the
previous year. Major inbound transactions included Preply’s aforementioned
USD150 million funding round and PZU SA’s agreement to acquire MetLife Ukraine.
With the number of inbound transactions doubling (rising
from five deals in H1 2025 to ten deals in H1 2026), disclosed inbound deal
value also increased significantly, up from just USD26 million to USD415
million over the same period. In terms of inbound sector activity, innovations
and technology led inbound investment, followed by banking and insurance and a
range of other sectors.
While foreign investment activity is still highly sensitive
to the security and macroeconomic conditions affecting Ukraine, this increase
in inbound transactions may indicate the early stages of a broader recovery in
investor interest in selected Ukrainian assets and sectors. A more
comprehensive assessment of these trends will be available in our full-year
2026 edition of M&A Radar: Ukraine.
Ukrainian companies continue strategic expansion abroad
Outbound M&A activity has remained stable, with five
transactions recorded in both H1 2025 and H1 2026, while Europe is still the
primary destination for Ukrainian acquisitions. In addition to MHP’s expansion
into the Greek food market, language software company Grammarly acquired
Portuguese data analytics startup Rows.com.
Dealmaking was not exclusive to Europe, however, with
Ukrainian companies expanding internationally through transactions in North
America and Asia-Pacific. Holywater’s USD22 million investment raise and Jiji’s
USD20 million acquisition of Bangladeshi marketplace Bikroy, for example,
provide examples of outbound activity in new markets for Ukrainian-founded
technology companies.
Outlook: Ukraine’s M&A market positioned for further growth in H2 2026
Transaction volumes remained stable in H1 2026 and, together with other supporting factors, suggest the market could see further increased activity during the second half of the year, with innovations and technology, agriculture, power and utilities, and consumer markets among the sectors likely to attract significant investment attention in H2 2026.
KPMG specialists note, however, that expanded war-risk insurance mechanisms and the fulfilment of investment plans announced by local and international investment funds (such as Horizon Capital and the US DFC) will be necessary to underpin short to medium-term prospects for the Ukrainian M&A market.
“Recent market activity suggests that investors continue to evaluate opportunities in Ukraine despite a challenging environment,” noted Svitlana Shcherbatyuk. “Recent deal activity, coupled with planned investment schedules and increased implementation of risk-mitigation instruments could support further deal activity as the year progresses.”
Read more about key transactions, investment trends, and market outlook in the report: M&A Radar H1 2026: Ukraine.
The military war may be swinging in our favor, but the information war continues.
Just as an army needs soldiers, so does a free society need its journalists to ensure that people have access to honest, trustworthy voices to understand the world around them.
For the past five years, The New Voice of Ukraine has been working tirelessly to push back against Russian narratives and defend democracy. But we cannot do it alone.
Please consider supporting us on Patreon for just $5 a month – your donation does directly to supporting journalists and ensuring that this front of the infowar says solid and defended.
Thank you.
Follow us on Twitter, Facebook and Google News
